The US fertilizer market – different nutrients with divergent stories
We speak to Justin Rackleff, CRU’s Americas Lead, Fertilizer Value Chain, about the US market state-of-play ahead of this year's Southwestern Fertilizer Conference.
We speak to Justin Rackleff, CRU’s Americas Lead, Fertilizer Value Chain, about the US market state-of-play ahead of this year's Southwestern Fertilizer Conference.
The UN Food and Agriculture Organization (FAO) and the International Fertilizer Association (IFA) have renewed their cooperation agreement to push more sustainable, evidence based fertilizer use and strengthen global agrifood resilience.
The International Finance Corporation, Siemens Financial Services and Fullerton Carbon Action Fund have signed definitive agreements for a total equity investment of $105 million in Hygenco Green Energies. The investment will support the development of multiple commercial green hydrogen projects which Hygenco aims to deliver as part of India’s National Green Hydrogen Mission. Hygenco broke […]
Controlled-release fertilizers (CRFs) can help food processors and consumer packaged goods (CPG) companies cut their Scope 3 emissions.
Karl Wyant, Nutrien's Director of Agronomy, discusses practical ways for improving potassium uptake by crops.
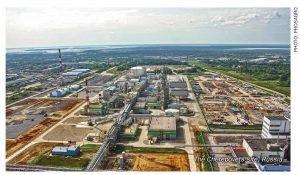
Multiple drone strikes have hit the industrial city of Cherepovets in Russia's Vologda Oblast region, according to Russian news agency TASS. The area contains PhosAgro's largest phosphate fertilizer production site. Cherepovets has a production capacity of around 700,000 t/a NPK and around 814,000 t/year DAP/MAP, according to CRU data, making it the largest phosphate fertilizer production site across Europe and the CIS. The site also contains several sulphuric acid plants with a combined capacity of 4.5 million t/a, making it Russia's largest production hub for the acid. This entire volume is consumed domestically.
CRU’s Phosphates+Potash Expoconference was held in Paris in mid-April, with the Iran crisis uppermost in everyone’s mind. Margins are under pressure, sulphur has become a strategic constraint, and the phosphates investment pipeline is thin. CRU Principal Consultant Humphrey Knight examined the fallout from the closure of the Strait of Hormuz, noting that fertilizers have been hit harder than most bulk commodities. A large share of exportable sulphur and traded urea normally originates in, or passes through, Gulf producers. The effective closure of the strait has squeezed the traded part of these markets, where international prices are set, and pushed benchmarks up sharply. The global phosphate market is structurally tight, and the combination of Chinese export policy and Middle East logistics has pushed the traded segment into a much more fragile state.
Morocco's OCP is bringing forward its maintenance schedule and expects a reduction of up to 30% in output for the second quarter of 2026, the company said 2 April, with some plants beginning maintenance next week.
Nitrogen markets, and urea in particular, have been impacted by a series of geopolitical shocks in recent years which have driven markets over and above normal market factors such as feedstock and shipping costs, crop prices etc.
A market already characterised by tight supply has been thrown into chaos by the Iran war and reduction of phosphate exports from the Gulf at the knock on effect on sulphur prices, a key input into MAP/DAP production.