Nitrogen+Syngas 403 Sep-Oct 2026
16 September 2026
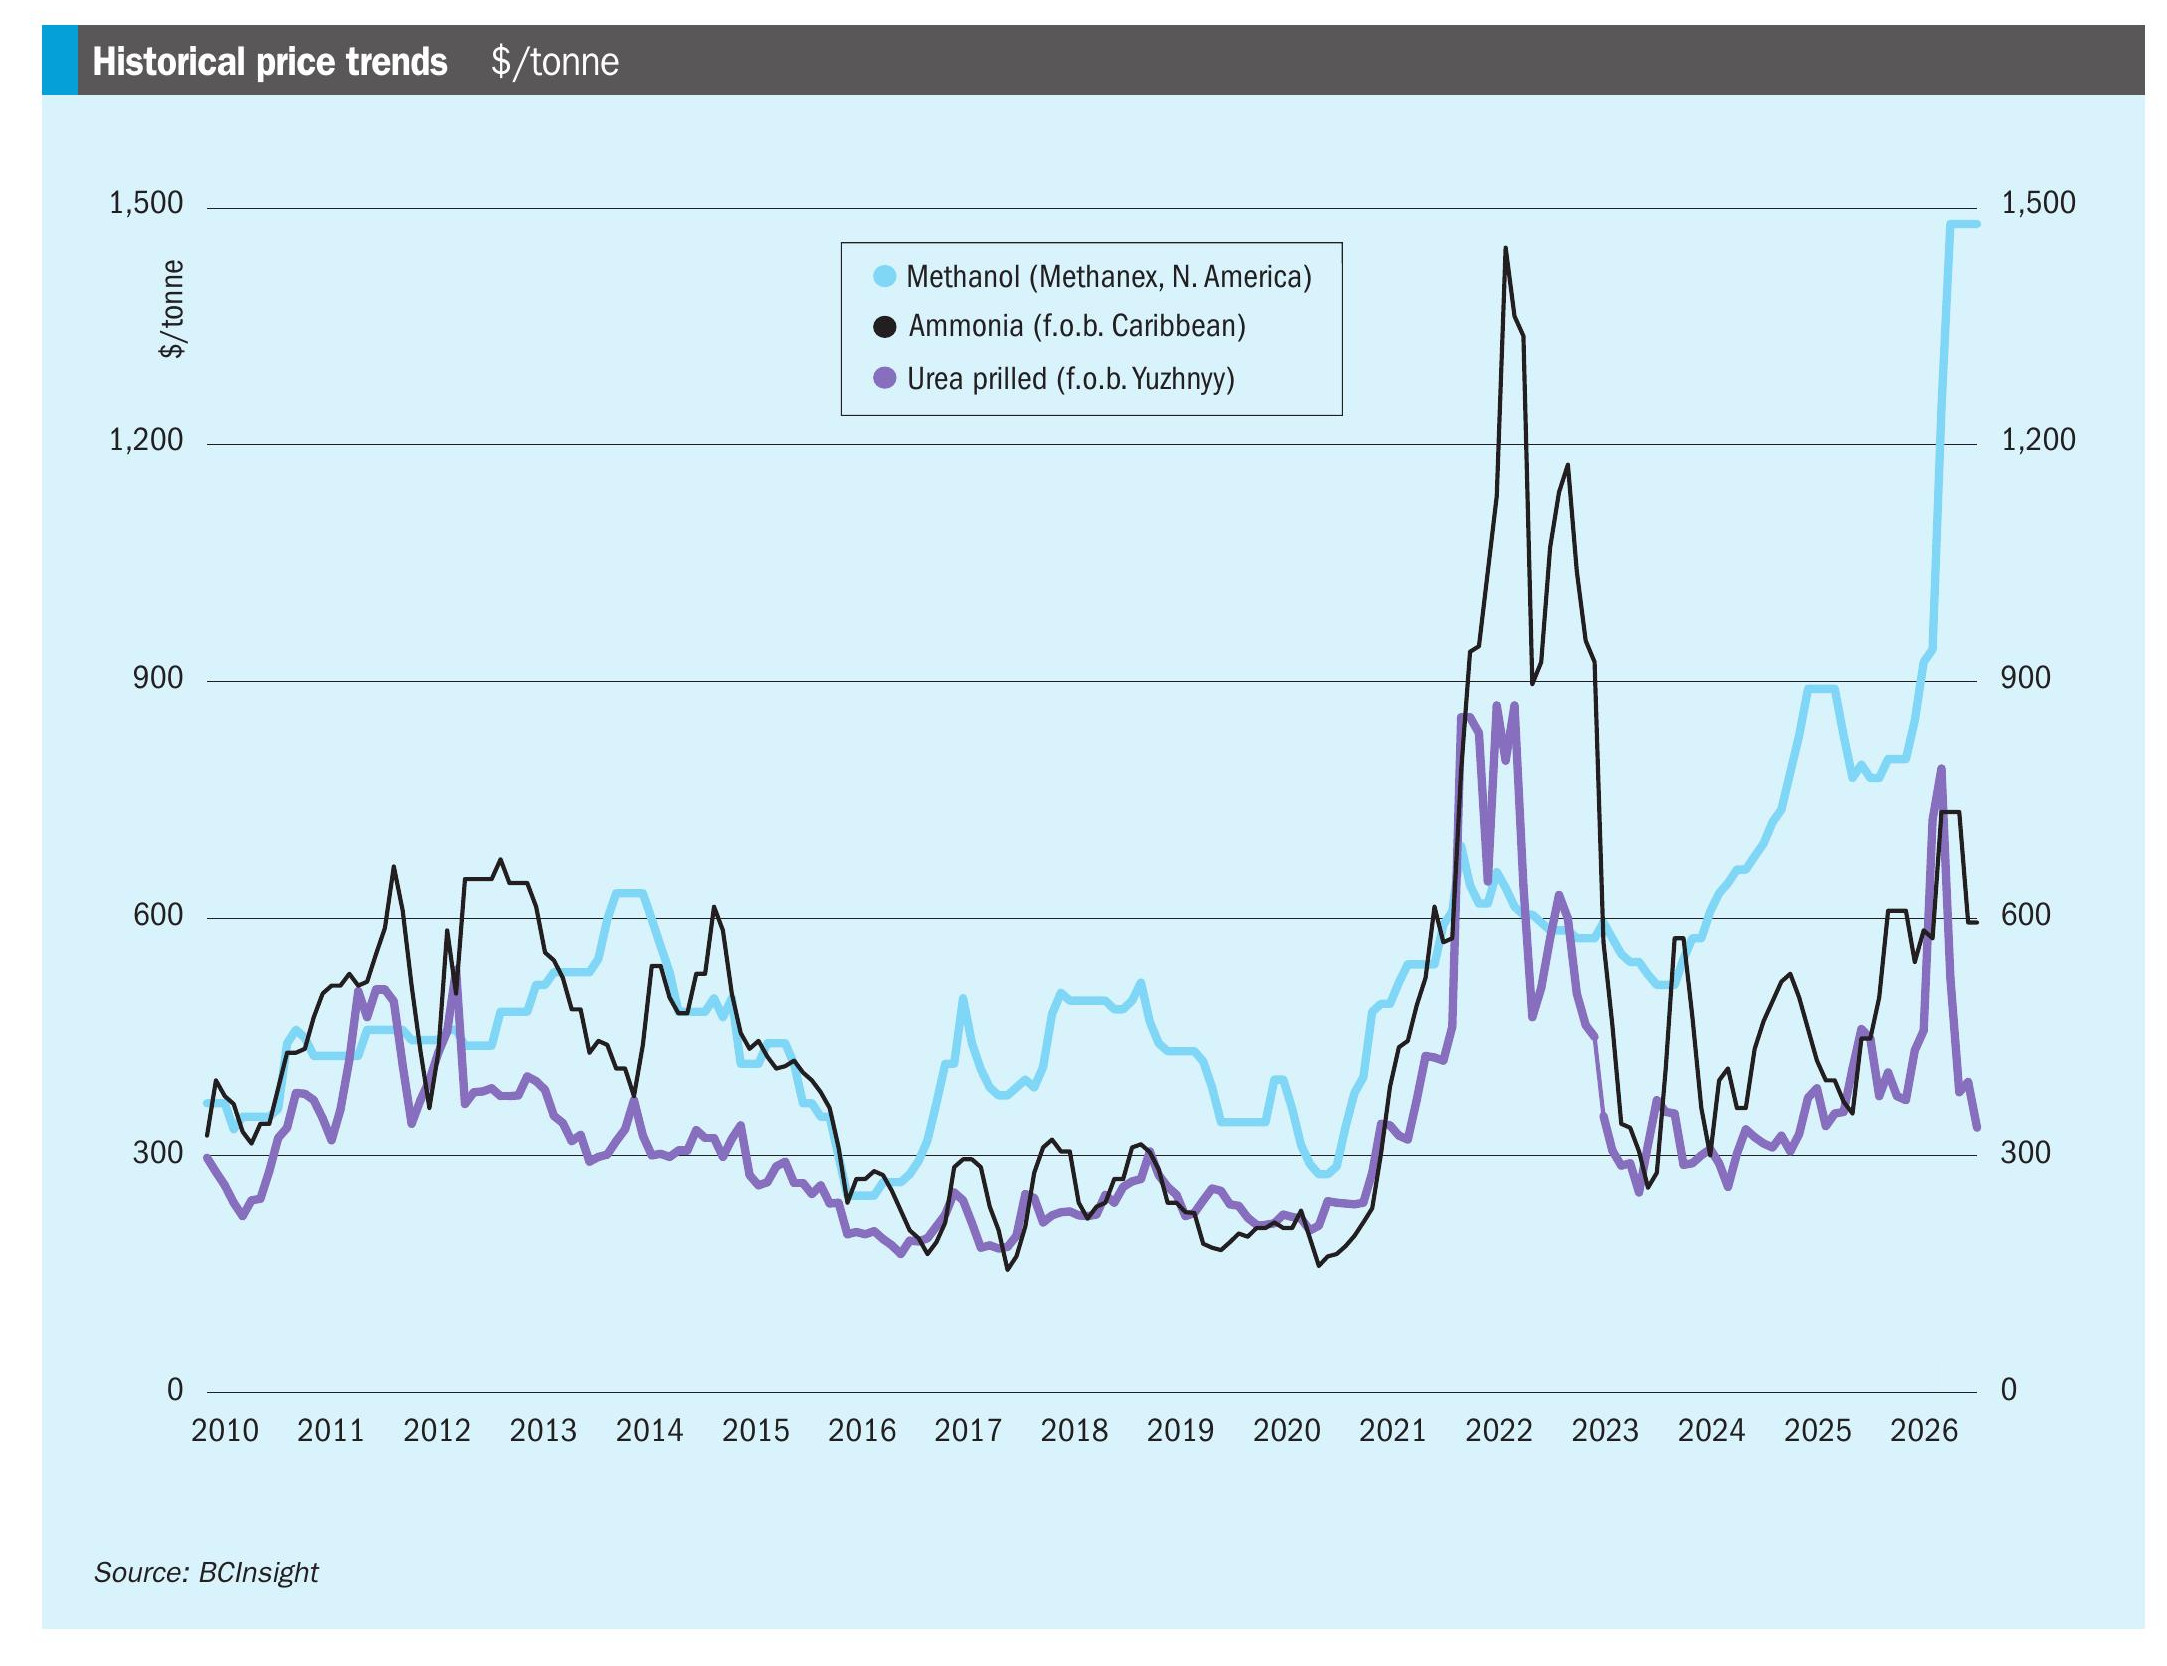
Price Trends
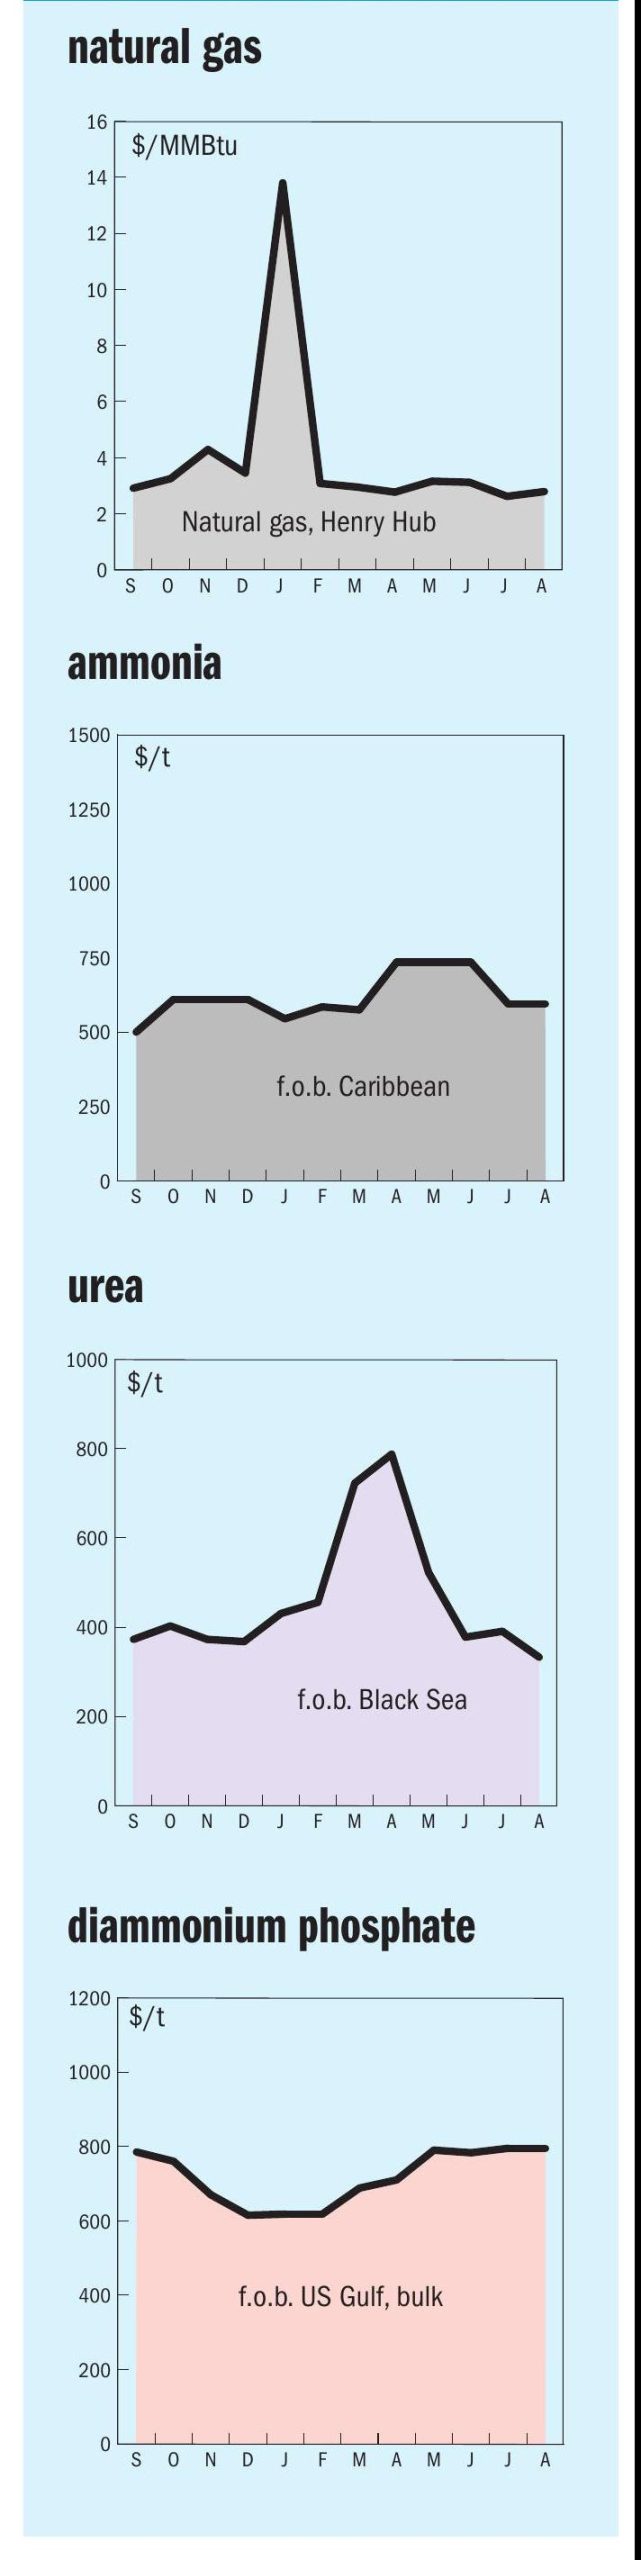
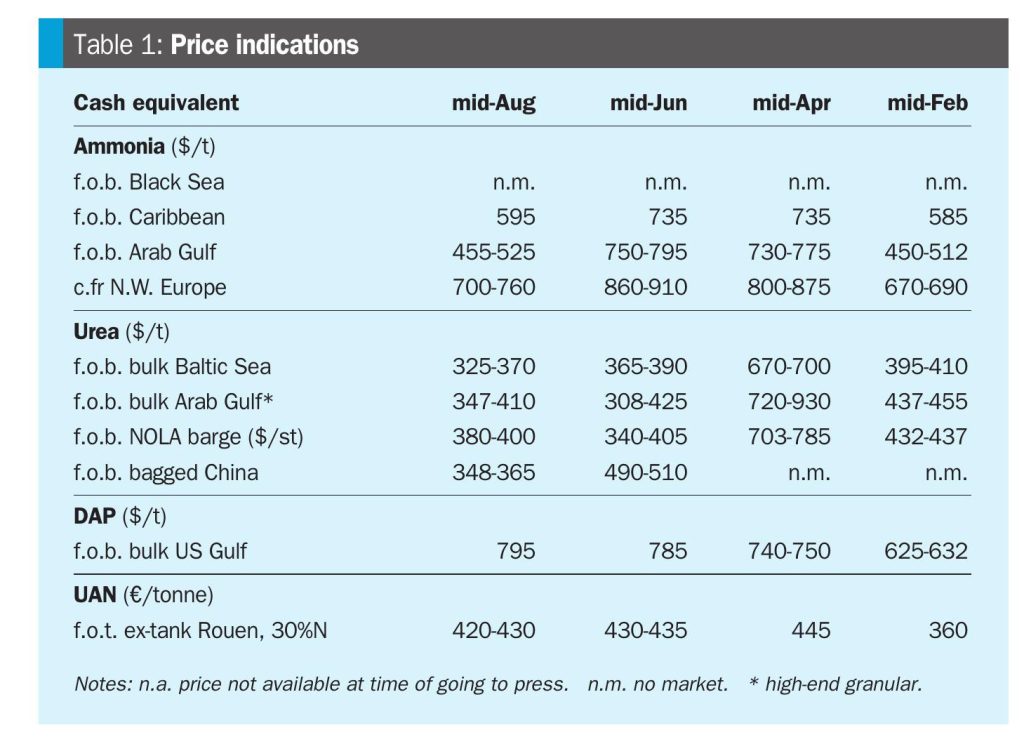
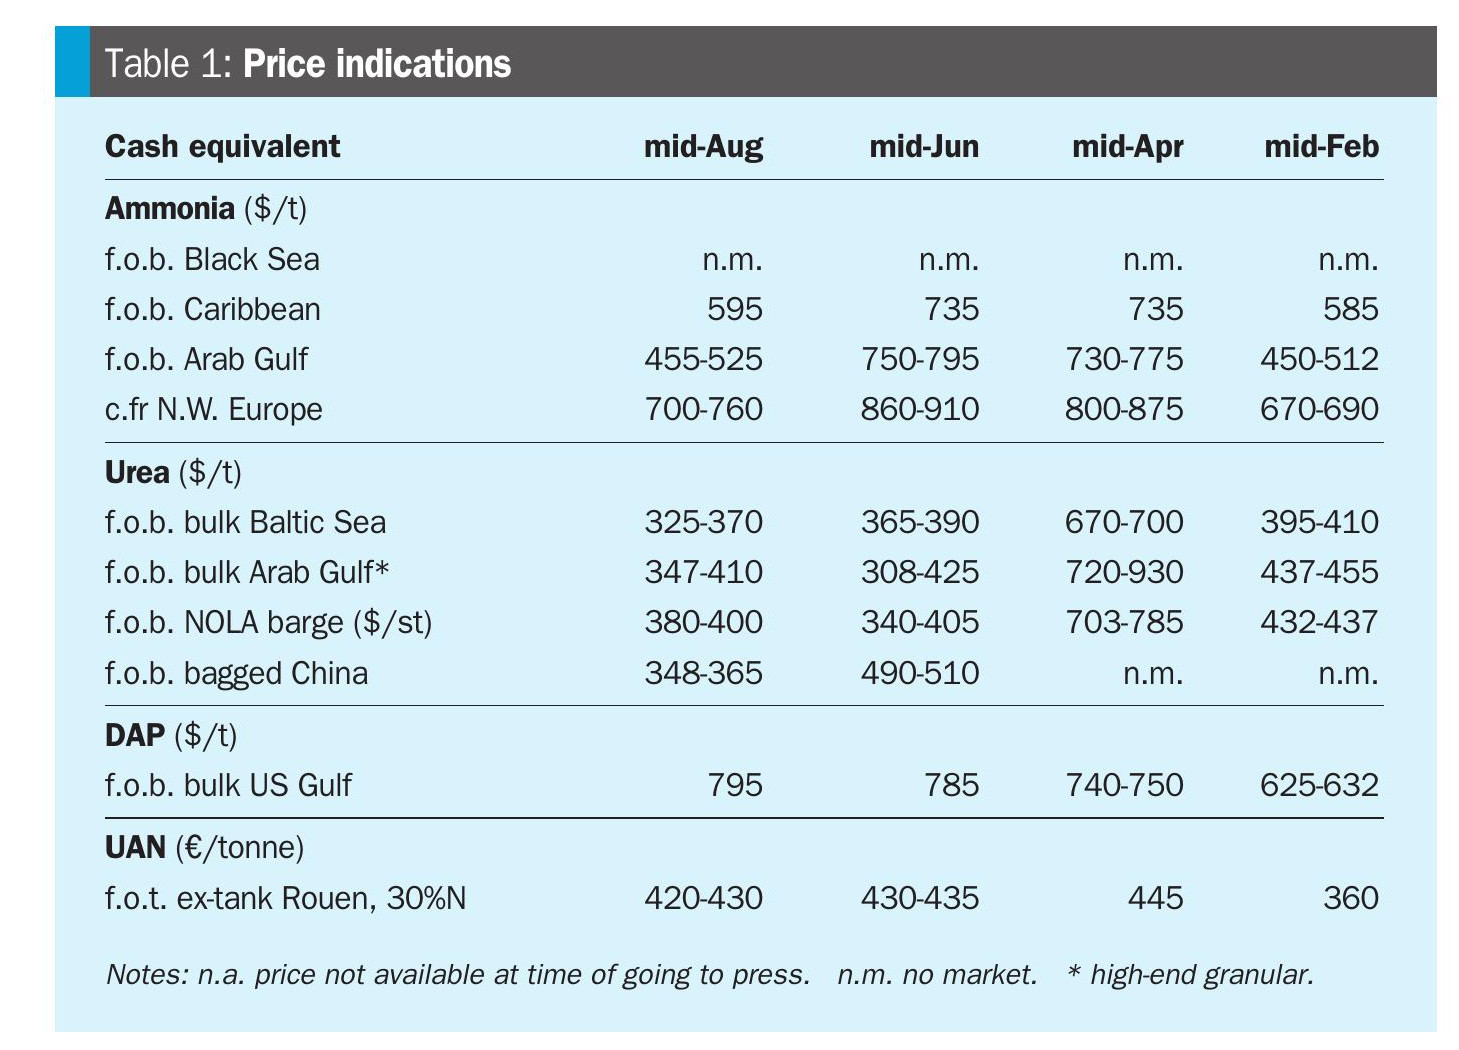
The ammonia market continued to be divided on a regional basis during August. In northwest Europe, prices remained high, holding above the $700/t CFR mark, underpinned by high Dutch TTF gas prices, which stood at €63.93/ MWh ($21.5/MMBtu) as of 20 August. The spot market was active, with two cargoes destined for CF Fertilisers in the UK, one an ex-Trinidad cargo supplied by Koch and the other an ex-Algeria cargo supplied by Trammo. Trammo was also linked to a separate, unconfirmed, sale into Poland for Grupa Azoty.
East of Suez, however, sentiment remained bearish. Chinese FOB offers in the $430/t range continued to anchor the regional floor, putting pressure on other producers. This was reflected in Southeast Asia, where the assessed price range eased to $420-500/t FOB amid growing length and a reported sale into India at $450/t CFR for Malaysian-origin material. However, significant regional buying interest is yet to emerge, with demand also muted in East Asia where inventories in South Korea and Taiwan, China remained sufficient for near-term needs.
In the US, the market was quiet, with attention now focused on the September Tampa contract settlement between Yara and Mosaic. Expectations were for a moderate decline from the August price of $635/t CFR, with most anticipating a settlement closer to $600/t CFR, reflecting the broader weakness outside of Europe.
The urea market saw pockets of price rally, but demand remained lacklustre. Prices for granular urea at New Orleans firmed after softening earlier in the month, with September barges trading between $403-405/st, following higher priced deals concluding in North Africa. In Egypt, sales were concluded by Mopco at $450/t FOB and Abu Qir at $475/t FOB, marking an increase on previous assessments. In Algeria, deals were also reported at progressively higher levels, reaching $467/t FOB following an AOA sale for September.
Overall, though, demand still remained muted, with the possibility of significant Chinese supply weighing on markets, while 10 vessels carrying around 442,000 tonnes of urea were still held west of the Strait of Hormuz. India closed a tender with lowest offers in the low-$390s/t CFR, expected to be largely supplied by China, with participation estimates ranging from 1.2-1.5 million tonnes.
In the Middle East, prices were indicated in the $390-410/t FOB range, with the logistical situation in the Strait of Hormuz still uncertain. In Iran, the official price was cut to $345/t FOB, though several tenders failed to attract buying interest.
In Southeast Asia, a tender from Brunei was rumoured to have been awarded in the $400s/t FOB, though other regional indications were heard as low as the $380s/t FOB. In Australia, delivered prices were revised down to the $450-490/t CFR range, amid ample import coverage for the current season.
European markets have been quiet. In the Baltic, prill prices slipped further, with two cargoes reportedly lined up to supply last week’s Indian tender. In the Black Sea, prices eventually climbed, mirroring gains in North Africa. In Northern Europe, prices in France were indicated lower at €480-485/t FCA amid scant demand.
END OF MONTH SPOT PRICES