Nitrogen+Syngas 403 Sep-Oct 2026
16 September 2026
Market Outlook
Market Outlook
AMMONIA
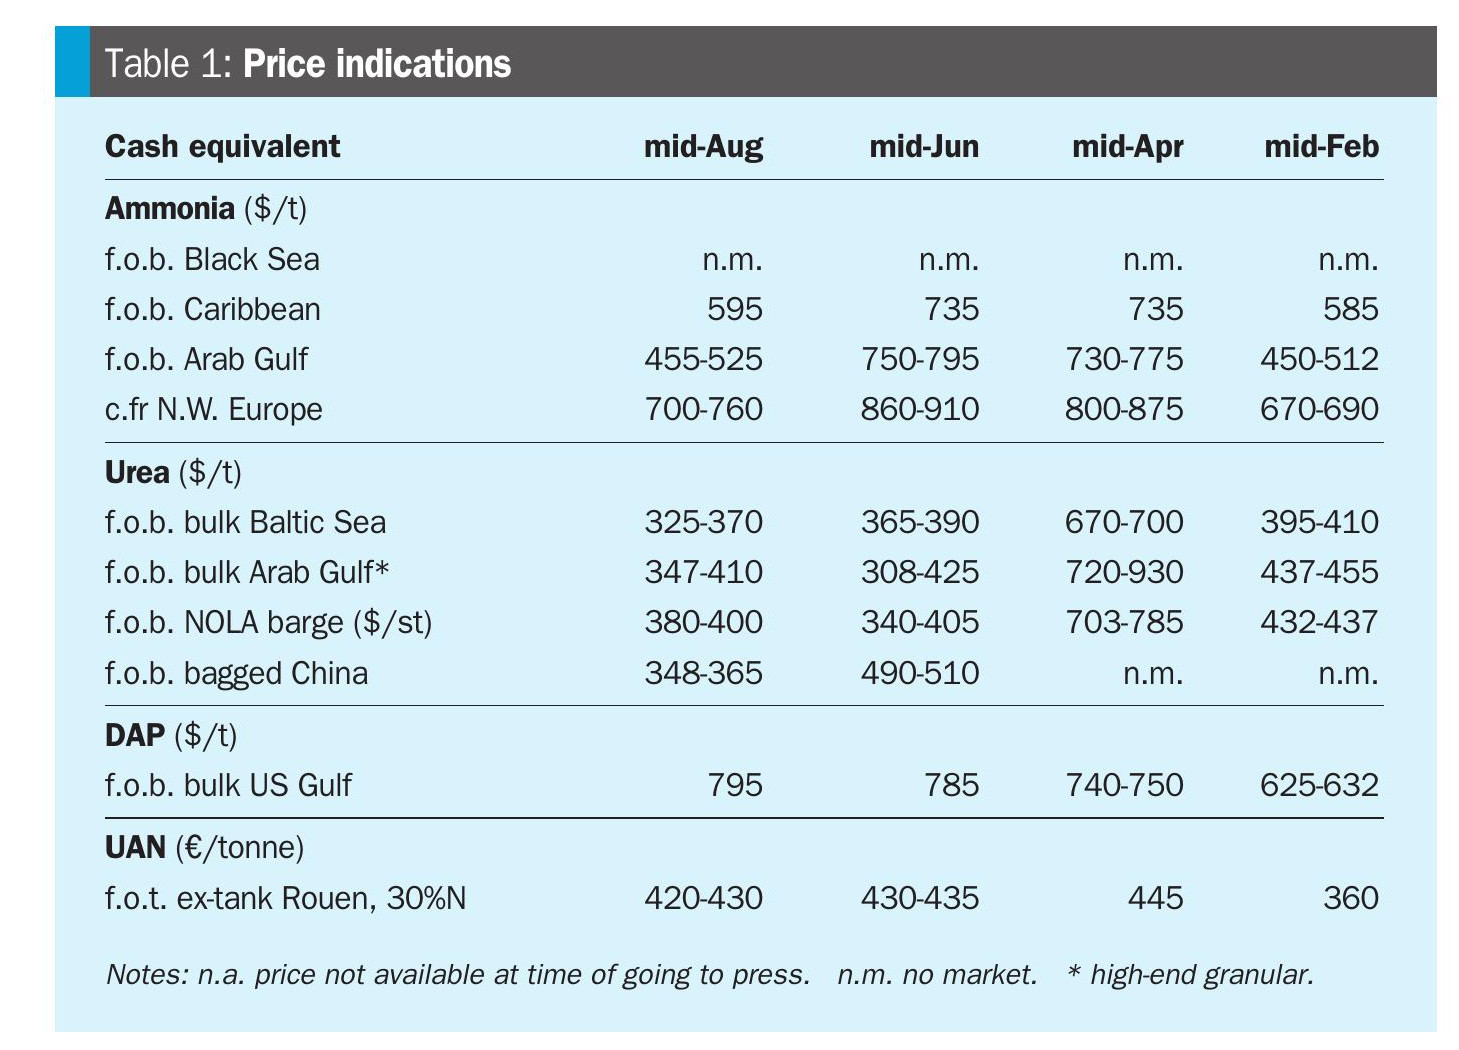
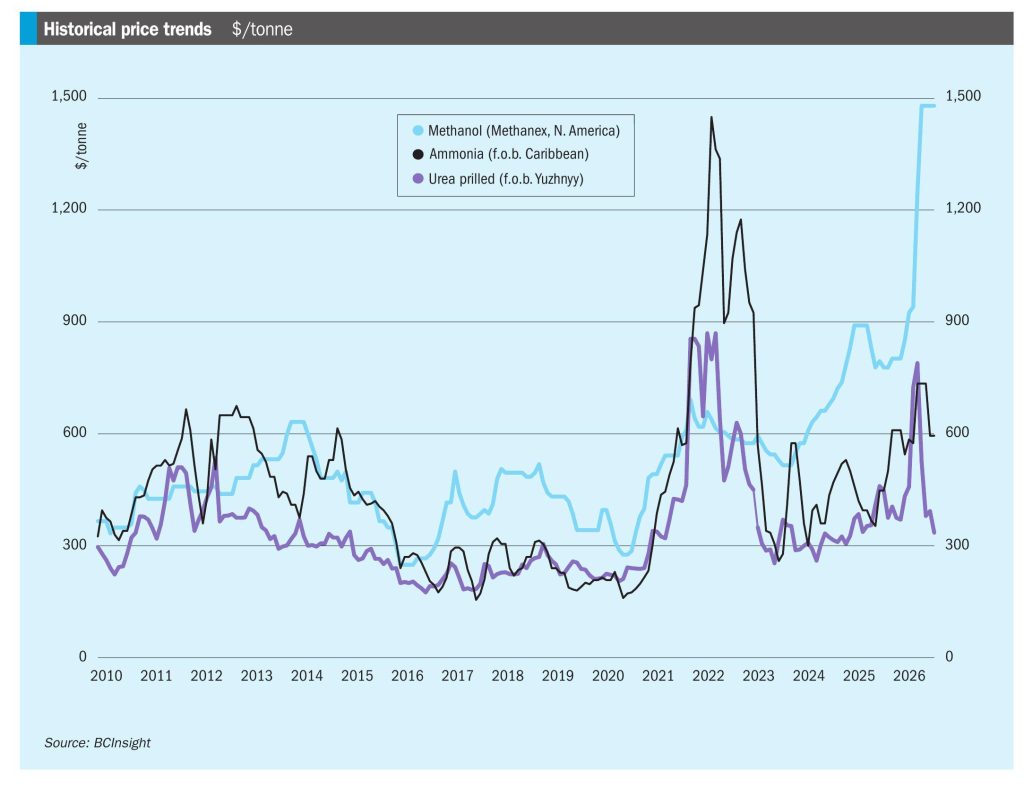
• Prices are expected to hold firm in Europe, though values elsewhere could well undergo further pressure, with Tampa also expected to decline for September.
• US attention was focused on September’s Tampa contract settlement between Yara and Mosaic. Expectations are for a moderate decline, with most alluding to an agreement at or close to $600/t CFR, down on August’s $635/t CFR figure. In the US Gulf, the August export lineup reached 237,000 tonnes by August 20th.
• Northwest European ammonia prices remain supported by increasing FOB indications out of Algeria. Dutch TTF gas prices at €63.93/MWh ($21.5/ MMBtu) also support such levels. Overall EU January-June ammonia imports were up by 4% year on year at 422,000 tonnes for 1H 2026.
UREA
• The urea market was looking to North Africa to see if the recent rally can be sustained through the remainder of August. August 24th saw Mopco sell 5,000 tonnes of granular at $490/t FOB for September shipment, and Abu Qir also placed 5,000 tonnes of granular at $490/t FOB. Both sales are $15/t up on prior activity.
• Chinese urea exports rose in July to 403,438 tonnes, bringing cumulative January–July exports to 907,058 tonnes, 41% up year on year. This surge followed China’s opening of its urea export window late May with two rounds “quota allocations” of around 5 million tonnes. The increasing export business has curtailed the downward trend in Chinese domestic prices, but – in addition to new capacity elsewhere – is holding regional and global urea prices down.
METHANOL
• The methanol market remains volatile, with continuing uncertainty over the situation in the strait of Hormuz. Around 4 million tonnes of methanol has not been produced and/or shipped since March, and two thirds of Iran’s methanol capacity remains down, with other Gulf producers running at reduced rates. With winter likely to shut down the remainder of Iranian capacity, further supply tightness lies ahead.
• Chinese domestic prices were rising, heading to $430/t at coastal ports, with feedstock coal supply remaining tight. Supply has risen as plants complete turnaround, while demand, is low for acetic acid and MTO, indicating lower prices may be ahead. Overall Chinese methanol demand may be down 3 million t/a for the year.
• Elsewhere, Southeast Asian methanol prices were around $505/t, the FOB US Gulf methanol market at 135 cents per gallon (ca $450/t); and European FOB Rotterdam prices at EUR 395/t.