• Skip to main content

    Tag: Prices

    Price Trends

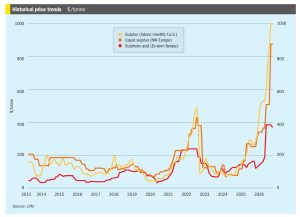
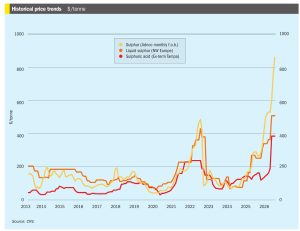
    The global sulphur market has entered a holding pattern, as a wave of bearish sentiment has so far failed to move stubbornly high spot prices. The departure of a significant volume of product from the Middle East has emboldened buyers and shifted market sentiment firmly towards bearish, but at time of writing this has so far failed to translate into lower prices. With sellers in no hurry to lower prices and spot availability still tight, the market has stalled as both sides wait for the other to blink first.

    Uncharted waters

    The fragile ceasefire between the United States and Iran broke down at the start of July, just three weeks after the signing of the June memorandum of understanding, after Iran fired at several vessels who had failed to notify them of their transit of the Strait of Hormuz, and the US retaliated with a missile barrage. While the two month negotiation period it had specified to solve all of the outstanding issues between the two parties had always seemed over-ambitious, market participants had at least expected to have that grace period to arrange for new cargoes and tranship them through the Strait. Now that the ceasefire has ended early, markets are truly entering uncharted waters.

    All this and El Niño too…?

    The August deadline for talks between the US and Iran came and went, as expected, with no resolution to the conflict. At time of writing, both sides were exchanging tit for tat attacks on ships in the Strait of Hormuz, with Iran claiming that it would be instituting a new ‘exclusion zone’, and no sign of a diplomatic resolution in sight. With the flow of ammonia, urea and other commodities like oil, LNG and sulphur from the Gulf still slowed to a trickle, the summer of high prices and demand destruction looks set to extend well into autumn at least.

    Price Trends

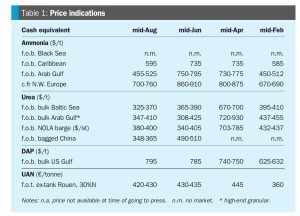
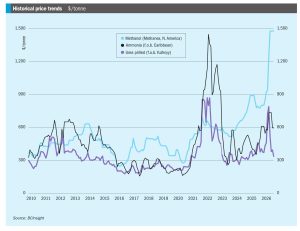
    The ammonia market continues be divided on a regional basis during August. In northwest Europe, prices remained high, holding above the $700/t CFR mark, underpinned by high Dutch TTF gas prices, which stood at €63.93/ MWh ($21.5/MMBtu) as of 20 August. The spot market was active, with two cargoes destined for CF Fertilisers in the UK, one an ex-Trinidad cargo supplied by Koch and the other an ex-Algeria cargo supplied by Trammo. Trammo was also linked to a separate, unconfirmed, sale into Poland for Grupa Azoty.