Market Insight
Price trends and market outlook, 21st August 2025
Price trends and market outlook, 21st August 2025
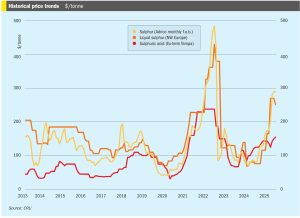
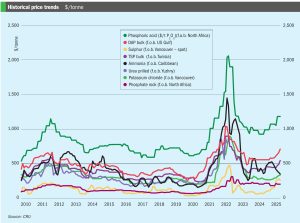
• Global sulphur prices are expected to experience decreases over the next few weeks. Buyers in Asia report that they are covered for contracted supply throughout July, and domestic prices in China are likely to decrease further, putting downward pressure on sulphur prices.
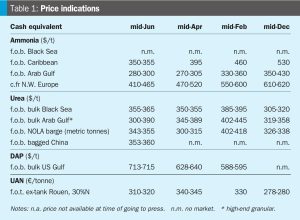
Ammonia benchmarks on both sides of the Suez were little changed in mid-June with a seemingly balanced supply-demand outlook, although those of a more bullish persuasion continue to support the notion that prices will soon – if they have not done so already – reach a floor. In Algeria, while activity was limited, producer Sorfert was believed to be seeking prices of $410415/t f.o.b. for July delivery, up $10-15/t and equivalent to >$450/t c.fr NW Europe. Imminent tariffs on imports of Russian fertilizers into the EU may trigger an uptick in downstream capacity utilisation across the continent.
Price trends and the market outlook, 19th June 2025
In this CRU Insight, Wahome Muya and Willis Thomas of CRU Consulting take a deep dive into the long-term prospects for potassium sulphate (SOP).
Global gas demand has returned to growth after the supply shock of 2022-23, but geopolitical tensions and short supply in LNG markets.

Support for ammonia prices in markets east of Suez eroded during February. The ongoing bubble of support seen in NW Europe remained just about intact, though news of further declines at Tampa for March and slumping natural-gas prices should begin to eat away at any remaining support in the West. After declining $70/t during the first two months of 2025, the Tampa settlement between Yara and Mosaic was revised down a further $40/t for March, imposing further downward pressure on f.o.b. values in Trinidad and the US Gulf.
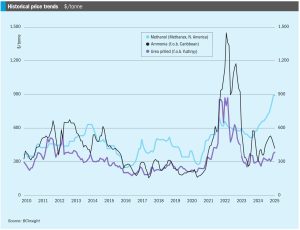
• Prices look set to come under further pressure moving into March, particularly east of Suez. Prices in the West – specifically in northwest Europe – have enjoyed a partial degree of support through February, though this appears unlikely to hold for much longer.
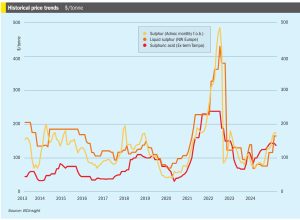
• Sulphur prices have been revised higher in the latest forecast after supply from the Middle East was lower than expected in February, and buyers with uncovered demand were forced to chase prices upwards. UAE sulphur exports normally fall at the start of the year due to scheduled maintenance, but sales in February this year were 200,000 tonnes short of what is typical. Prices may climb more than expected as buyers scramble to cover their shorts. If supply is slower to return than currently anticipated, momentum may push prices even higher in the short term.
Philippine Associated Smelting and Refining (PASAR) has put its plant on Leyte Island into care and maintenance to evaluate the operation amid what it termed as increasingly challenging market conditions.