
The future of hydrogen
Low emissions hydrogen is expected to play an increasing role in the syngasbased chemicals industry, but cost and technical challenges remain.
Low emissions hydrogen is expected to play an increasing role in the syngasbased chemicals industry, but cost and technical challenges remain.

Prices in the West are unlikely to garner much support moving into the latter stages of Q2. The May Tampa ammonia settlement was settled by Yara and Mosaic at $450/t c.fr, down $25/t on the $475/t c.fr agreed for April. With seasonal domestic demand in the US drawing to a close 2H April, many had anticipated that either a rollover or a slight decline would be agreed.
Nitrogen+Syngas’s annual listing of new ammonia, urea, nitric acid and ammonium nitrate plants.
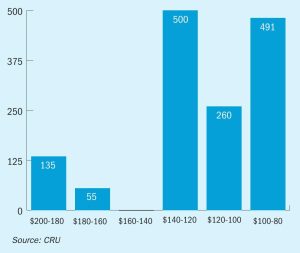
Sulphur prices reached a low point in mid-February, with buyers looking to the tender from Muntajat as well as the return of Chinese buyers following the Lunar New Year holiday for the direction that the market would turn. CMOC’s 5 February tender for 40,000 tonnes of sulphur for early-April arrival was indicated awarded in the upper $90s/t c.fr on supply from the FSU, though details were not confirmed.
China’s drive to build new battery production capacity for electric vehicles and stationary storage is leading to a familiar problem for the Chinese economy; overcapacity.
The phosphate industry, the dominant consumer of sulphuric acid worldwide, has grown to its present size on the back of fertilizer consumption. And while this has seen considerable growth over the past decades, especially in countries like China, India and Brazil, it has generally been fairly steady and – subject to the annual vagaries of weather and the commodity cycle – relatively predictable. However, the world economy is now in the throes of a major transformation towards less carbon intensive generation and use of energy, and that is disrupting many markets, including that for phosphates.
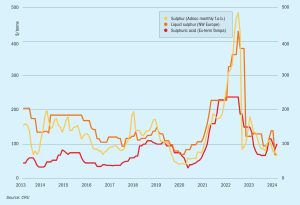
CRU expects sulphur prices to be supressed in early 2024 by high port inventory and limited phosphate export business. However, affordability continues to support raw materials purchases and leaves room for price increases, especially if downstream production picks up as expected and sulphur stock drawdown slows.
More than 900 delegates from 400 companies and 56 countries gathered at the Hilton Downtown Hotel, Miami, Florida, 5-7 February, for the 2024 Fertilizer Latino Americano (FLA) conference. The event was jointly convened by Argus and CRU. We present selected highlights from this year’s three-day conference.
Fertilizer International spoke to Matt O’Leary , the MD of Aquifert, about the state of the water-soluble fertilizer (WSF) market at the 2024 Fertilizer Latino Americano Conference in Miami in February.
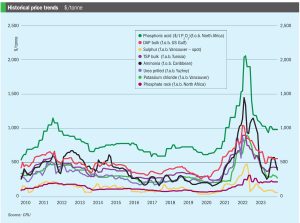
Urea. As February ended, urea prices found support in the US and Brazil while Europe remained subdued and Egypt struggled to find buyers. New Orleans was the one bright spot in the urea market – with NOLA prices benefitting from the meeting of suppliers and buyers at the TFI’s domestic conference. With positive sentiment all round, prices moved up $30/st, peaking at $390/st f.o.b. for March.