Sulphur 426 Sep-Oct 2026
18 September 2026
Middle East phosphate production
Ambitious expansion plans face exposure to trade route disruption.
The Middle East is one of the world’s major phosphate exporting regions and hence a significant consumer of sulphur and sulphuric acid. However, for some countries in the region, ambitious expansion plans face unusually acute exposure to trade-route disruption. Saudi Arabia remains the principal regional force in export-oriented phosphate fertilizers, while Jordan retains an established role in phosphoric acid and finished fertilizers. Egypt is advancing projects intended to extend downstream processing around domestic phosphate resources, and the United Arab Emirates has a number of prospective, but still speculative, projects associated with Ruwais.
However, the disruption of shipping through the Strait of Hormuz has demonstrated that physical production capacity and deliverable supply are not the same thing. It has constrained the ability of Saudi producers to reach export markets, while also interrupting sulphur availability – a critical input into phosphoric acid and phosphate fertilizer manufacture.
Saudi Arabia
Saudi Arabia is the Middle East’s most important integrated phosphate fertilizer producer. Its industrial system combines phosphate resources, processing capacity, ammonia availability and export infrastructure, with Ma’aden and its partner SABIC central to the sector. The country’s established phosphate supply chain is orientated towards the Arabian Gulf, notably around Ras Al-Khair and Jubail.
At Ras Al-Khair, Ma’aden has approximately 3.3 million t/a of DAP and MAP capacity, together with around 1.5 million t/a of phosphoric acid capacity (tonnes P2O5 ). A further facility at Jubail has approximately 500,000 t/a of DAP capacity.
But much of Saudi Arabia’s phosphate export system has been designed around Gulf access, leaving exports heavily dependent on passage through the Strait of Hormuz. Since the closure of the Strait at the end of February 2026, moving phosphate fertilizers from Saudi plants to customers has become substantially more difficult. Alternative arrangements have included trucking material to Red Sea ports, particularly Yanbu and Neom. Some volumes have also moved through Duqm in Oman. These options preserve some export capability, but they impose additional transport, handling and scheduling costs, and are not direct substitutes for a fully functioning export system. Furthermore, exports east via the Red Sea must still run the gauntlet of Houthi rebel attacks around the Bab al-Mandab Strait.
The immediate consequence has been a sharp reduction in exports and the accumulation of inventory. Up to 600,000 tonnes of Saudi phosphate fertilizer was reported to have been stranded in the Gulf at one point. Although a significant portion of this material reportedly moved during the June and July ceasefire period, the episode showed the significance of maritime access in converting nominal capacity into market supply.
At present Ma’aden may be able to export approximately 300–400,000 t/month while the Strait remains unavailable. This is meaningful volume, but below the level that a fully operational export network could support. Saudi DAP and MAP exports are forecast at 4.6 million t/a in 2026, despite the disruption. On a broader DAP, MAP and TSP basis, Saudi exports are projected to fall from approximately 6.5 million t/a in 2025 to 4.7 million t/a in 2026 – a decline of around 25%.
Ma’aden III
The most important addition to Saudi Arabia’s phosphate sector is Ma’aden Phosphate III at Wa’ad Al-Shamal. The project is expected to provide 3 million t/a of DAP and MAP capacity in two phases. The project was previously expected to commission by the end of 2026, although regional tensions and export disruption create a risk to ramp-up and the timing of commercial operation. The project includes 760,000 t/a of wet-process phosphoric acid capacity, (tonnes P2 O5 ), together with forecast finished-product capacity equivalent to around 583,000 t/a P2 O5 as DAP and 208,000 t/a P2 O5 as MAP. It also includes capacity for NPK products. The project would add a new large-scale export-oriented production platform to Saudi Arabia’s existing facilities, extending the country’s ability to serve markets in South Asia, Africa and elsewhere. It also reinforces a broader pattern in phosphate markets: new capacity is increasingly concentrated in integrated, resource-backed systems. Saudi Arabia has an advantage in this regard because its phosphate operations sit within a wider industrial base capable of supplying ammonia, power, infrastructure and export logistics. However, 2026 has also shown that integration at the plant level does not eliminate exposure to external maritime routes.
Jordan
Jordan remains a significant Middle Eastern phosphate producer, centred on Jordan Phosphate Mines Company (JPMC) and its facilities at Aqaba. JPMC operates DAP capacity at Aqaba equivalent to approximately 110,000 t/a P2O5, alongside MAP capacity of around 40,000 t/a P2 O5. The Aqaba location gives Jordan access to the Red Sea. Capacity additions include the proposed joint venture with Turkey’s Transpet, developing 300,000 t/a of phosphoric acid capacity, and associated sulphuric acid capacity. Tendering concluded in June with construction to start soon. Jordan has an established export-oriented phosphate industry, but the picture is one of continued activity around phosphoric acid and phosphate conversion, with the timing and realisation of individual proposals remaining uncertain.
Egypt
Egypt’s phosphate developments are focused on building or expanding downstream conversion capacity at Abu Tartour and Ain Sokhna. At Abu Tartour, activity is based around the El Wady for Phosphate Industries and Fertilizers (WAPHCO). The project involves the construction of a phosphoric acid plant with a production capacity of 500,000 t/a of phosphoric acid and 1.6 million t/a of sulphuric acid, supporting the downstream processing of locally mined phosphate rock. Phase 1 of the development represents an investment of approximately US$658 million and will produce 250,000 t/a of phosphoric acid.
Misr Phosphates, a 25% stakeholder in WAPHCO, also has a plan to develop a DAP/MAP/NPK plant at Ain Sokhna in northeast Egypt, including 518,000 t/a of wet-process phosphoric acid capacity, plus finished-product capacities equivalent to 230,000 t/a P2O5 for DAP, 156,000 t/a P2O5 for MAP and 276,000 t/a P2O5 for TSP.
A separate project by El-Nasr Company for Intermediate Chemicals (NCIC) at Ain Sokhna is expected to add approximately 392,000 t/a P2O5 of wet-process phosphoric acid capacity from 2028, as well as DAP and MAP capacity equivalent to approximately 83,000 t/a and 94,000 t/a P2O5 respectively. The location in the Suez Industrial Zone is notable because it links processing potential with access to Egyptian ports and the Suez trade corridor.
Egypt’s prospective projects point to a strategic direction of moving beyond phosphate rock extraction and toward higher-value acid and fertilizer production.
UAE
The United Arab Emirates is also a potential site for phosphate fertilizer production in the region, courtesy of ADNOC’s strategic tie-up with Morocco’s OCP. OCP has the world’s largest phosphate rock reserves and some of the lowest cost production, while the Emirate of Abu Dhabi has become the world’s leading exporter of sulphur. A strategic plan launched in 2018 intended that ADNOC would supply sulphur to OCP under a long-term contract, but also provided for the potential development of a phosphate hub at Ruwais in Abu Dhabi using imported Moroccan phosphate rock. The project proposes phosphoric acid capacity of around 450,000 t/a P2 O5, plus DAP and MAP capacities equivalent to around 225,000 t/a and 180,000 t/a. The development remains highly speculative. Nevertheless, Ruwais is a logical location for a potential integrated phosphate project. It is already a major industrial and energy hub, with established ammonia production and ample gas reserves for expansion. A partnership involving ADNOC and OCP could potentially combine industrial infrastructure and energy capability with phosphate-sector expertise and acid supply.
Sulphur supply
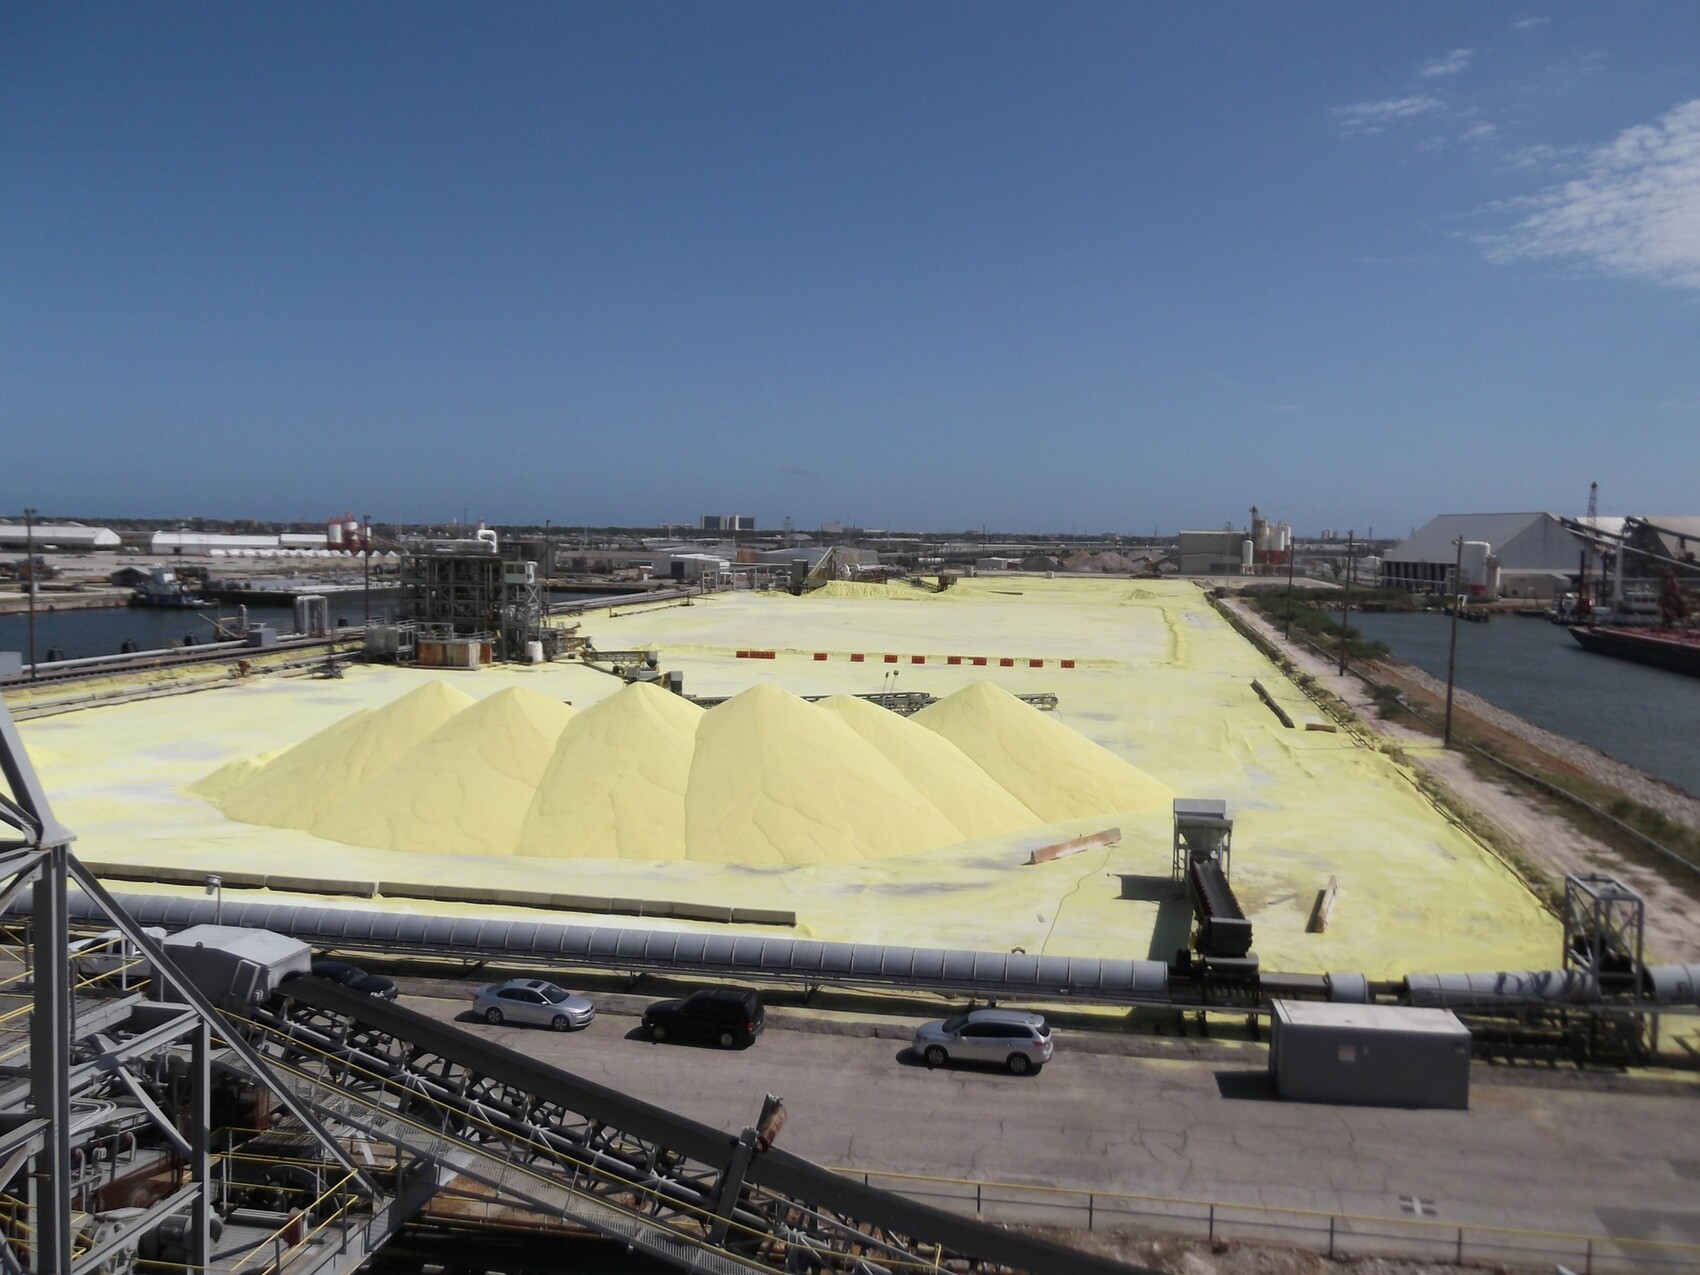
Phosphate production depends fundamentally on sulphur. Sulphuric acid is required to convert phosphate rock into phosphoric acid, which can then be used in DAP, MAP, TSP and compound fertilizers. This means disruptions in sulphur availability have a direct effect on the phosphate industry, even where mines and fertilizer plants themselves remain operational.
The 2026 Middle East conflict and closure of the Strait of Hormuz have tightened sulphur availability sharply. Middle Eastern sulphur suppliers have been described as operating at approximately half their normal capacity. Sulphur prices have consequently risen to levels that make it the largest component of phosphate production costs for many producers.
Forecast sulphur FOB Vancouver prices average around $912/t in 2026 and $928/t in 2027, compared with $302/t in 2025. While Saudi and Moroccan producers are indicated to retain comparatively strong phosphate margins, the price increase changes the operating environment across the industry. It can weaken the economics of less integrated producers and constrain output where sulphur cannot be sourced reliably.
The relationship between sulphur and phosphate supply also magnifies the implications of maritime disruption. The Strait of Hormuz is not only an export route for Saudi finished fertilizer; it is part of the logistics chain affecting regional sulphur movement. A protracted closure would therefore restrict both the movement of finished products and the availability of a vital production input.
Outlook
The Middle East phosphate industry has a substantial expansion agenda. Saudi Arabia’s Ma’aden Phosphate III is the foremost project and would materially increase regional DAP and MAP capacity once fully operational. Jordan continues to develop its acid and fertilizer position, while Egypt is pursuing new downstream processing capacity. However, the near-term supply picture remains more constrained. Saudi Arabia’s existing production base has been affected primarily by export logistics, while regional sulphur tightness has raised costs and complicated operations across phosphate value chains. The global traded volume of DAP, MAP and TSP is forecast to fall from 33.8 million t/a in 2025 to 27.8 million t/a in 2026, reflecting the magnitude of the supply disruption.
For Middle Eastern producers, the defining operational question is not simply how much capacity can be built, but how reliable the whole production chain is, from phosphate rock, sulphur, ammonia, and production plants, to ports and shipping corridors. The projects now under development could strengthen the region’s share of global phosphate supply over the latter part of the decade, but this year’s lesson has been that production capability, input availability and export access must all be considered together.