Asia
23 June 2026
CRU launches Indonesia acid price as nickel sector lifts demand
Written by Carrie Whymark & Viviana Alvarado
As Indonesia’s nickel industry drives significant import demand of sulphuric acid in recent years, CRU is launching a new weekly CFR Indonesia acid price assessment on 28 May to bring transparency to this key spot market.
Over the past five years, Indonesia has emerged as a key player in the sulphuric acid market, driven primarily by the rapid expansion of its nickel industry.
Growing interest in the battery materials sector has triggered a wave of high-pressure acid leach (HPAL) projects, with Indonesia at the centre of these additions. As a result, nickel-related acid demand has surged to 16 Mt/year in 2025 from 3.5 Mt/yr in 2021.
Alongside this rapid growth in demand, domestic acid production has also increased, supported by a combination of integrated acid units at nickel operations and new smelter capacity. Sulphur-burnt acid is the main source of acid in Indonesia amid the increased sulphur burning capacity in the country.
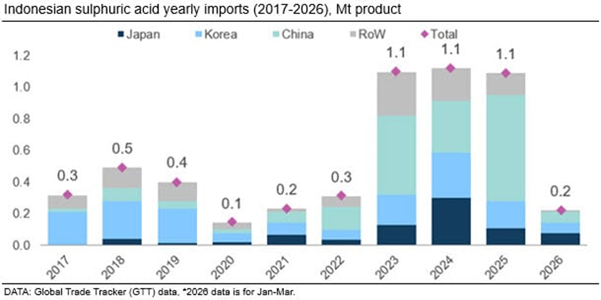
However, despite rising local output, Indonesia’s acid requirements have outpaced supply. While sulphur imports meet most demand, faster-than-expected expansion of HPAL capacity has driven a sharp rise in acid import needs. Acid import volumes have increased steadily, reaching 1.0 Mt in 2025, equivalent to a 47% CAGR since 2021.
The supply mix for these imports has also evolved. The market saw a pivotal shift in 2023 when total import volumes surged by over 250% year-on-year, jumping from around 0.31 Mt in 2022 to nearly 1.1 Mt. This initial demand was primarily met by increased flows from Japan and South Korea.
However, China emerged as the single largest supplier in 2025, shipping over 670,000 t. This trend has continued into the current year; for the first quarter of 2026, Indonesia imported 220,652 t, sourced almost evenly from its three main partners: Japan (77,259 t), South Korea (67,949 t), and China (67,642 t).

This new benchmark will provide essential price clarity for a market now defined by spot purchasing.
The new assessment builds on CRU’s price tracking since the start of 2026, which has already captured significant market volatility. The year began with relative stability, as prices held within a $150-185/t CFR range through the first quarter.
In April, however, tighter global supply and consistent spot demand from the HPAL sector pushed prices sharply higher, reaching $380-410/t CFR at the end of May. This represents an increase of more than 160% since January and demonstrates the market’s sensitivity to global supply shifts and the need for a consistent weekly reference.
CRU ensures that subscribers are equipped with the insights they need to navigate a rapidly evolving market. To find out more about our fertilizer price assessments, market data and analysis, please get in touch.