CRU Phosphates +Potash welcomes you to Paris!
CRU will convene the 2026 Phosphates+Potash Expoconference in Paris, France, at the Paris Marriott Rive Gauche Hotel, 13–15 April.
CRU will convene the 2026 Phosphates+Potash Expoconference in Paris, France, at the Paris Marriott Rive Gauche Hotel, 13–15 April.
A complete listing of all articles and news items that appeared in Fertilizer International during 2025.
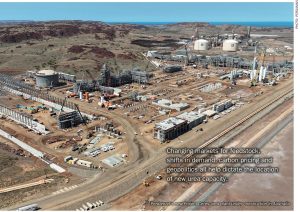
Changing markets for feedstock, shifts in demand, carbon pricing and geopolitics all help dictate the location of new urea capacity.
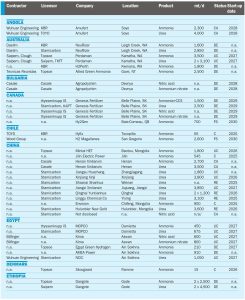
Nitrogen+Syngas ’s annual listing of new ammonia, urea, nitric acid and ammonium nitrate plants.
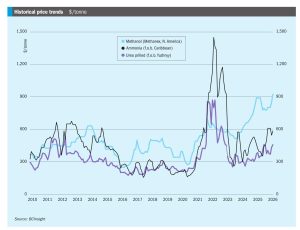
• Prices are likely to remain on an upward trajectory as long as the Strait of Hormuz remains effectively closed and Middle East export availability is constrained.
In just its first two months, 2026 had already managed to be a rollercoaster of a year, but at the start of March, the onset of hostilities against Iran by the US and Israel has managed to deliver another huge shock to markets, particularly commodities. Iran’s strategy of widening the conflict to neighbouring states, including by attacking Qatar’s massive LNG facility at Ras Laffan, effectively shutting it down, has sent the LNG market into chaos, and attacks on several tankers and other ships have paralysed maritime insurance markets and by default achieved the long-feared closure of the Straits of Hormuz.
Methanol’s phenomenal growth in the early years of the century was based on its uptake into fuel uses and its ability to bridge coal reserves with plastics production in China. However, with these sectors maturing, traditional chemical end uses are becoming the main growth sector once again.
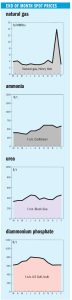
Ammonia sentiment was overtaken this week by the escalating Middle East conflict and the effective closure of the Strait of Hormuz, which left vessels unable to enter or exit the Arabian Gulf. With maritime trade frozen, price indications for prompt Middle East business largely stalled. In normal conditions, the sudden removal of Gulf export flows would point to sharply higher prices, particularly given the already-tight global availability and surging urea values, but participants said the absence of tradable cargoes made it difficult to pin down an indication. The immediate knock-on was felt East of Suez, where the supply shock pulled southeast Asian values back up to around $470-480/t f.o.b. Prevailing length in the market has been reportedly absorbed, with buying interest strongest from east Asia and India.
CRU’s annual Sulphur+Sulphuric Acid Expoconference was held from November 3rd to 5th, at The Woodlands, Texas.
The deficit in the sulphur market has led to a new focus on melting down and selling stockpiles of sulphur around the world. From Kazakhstan to Canada, stocks of sulphur have been shrinking.