Fertilizer International 506 Jan-Feb 2022
31 January 2022
Fertilizer Index 2021
A complete listing of all articles and news items that appeared in Fertilizer International during 2021




Fertilizer International 506 Jan-Feb 2022
31 January 2022
A complete listing of all articles and news items that appeared in Fertilizer International during 2021
The scale up of low carbon hydrogen has proved slower, more selective and more geographically concentrated than the ambitious plans announced earlier in the decade had anticipated.
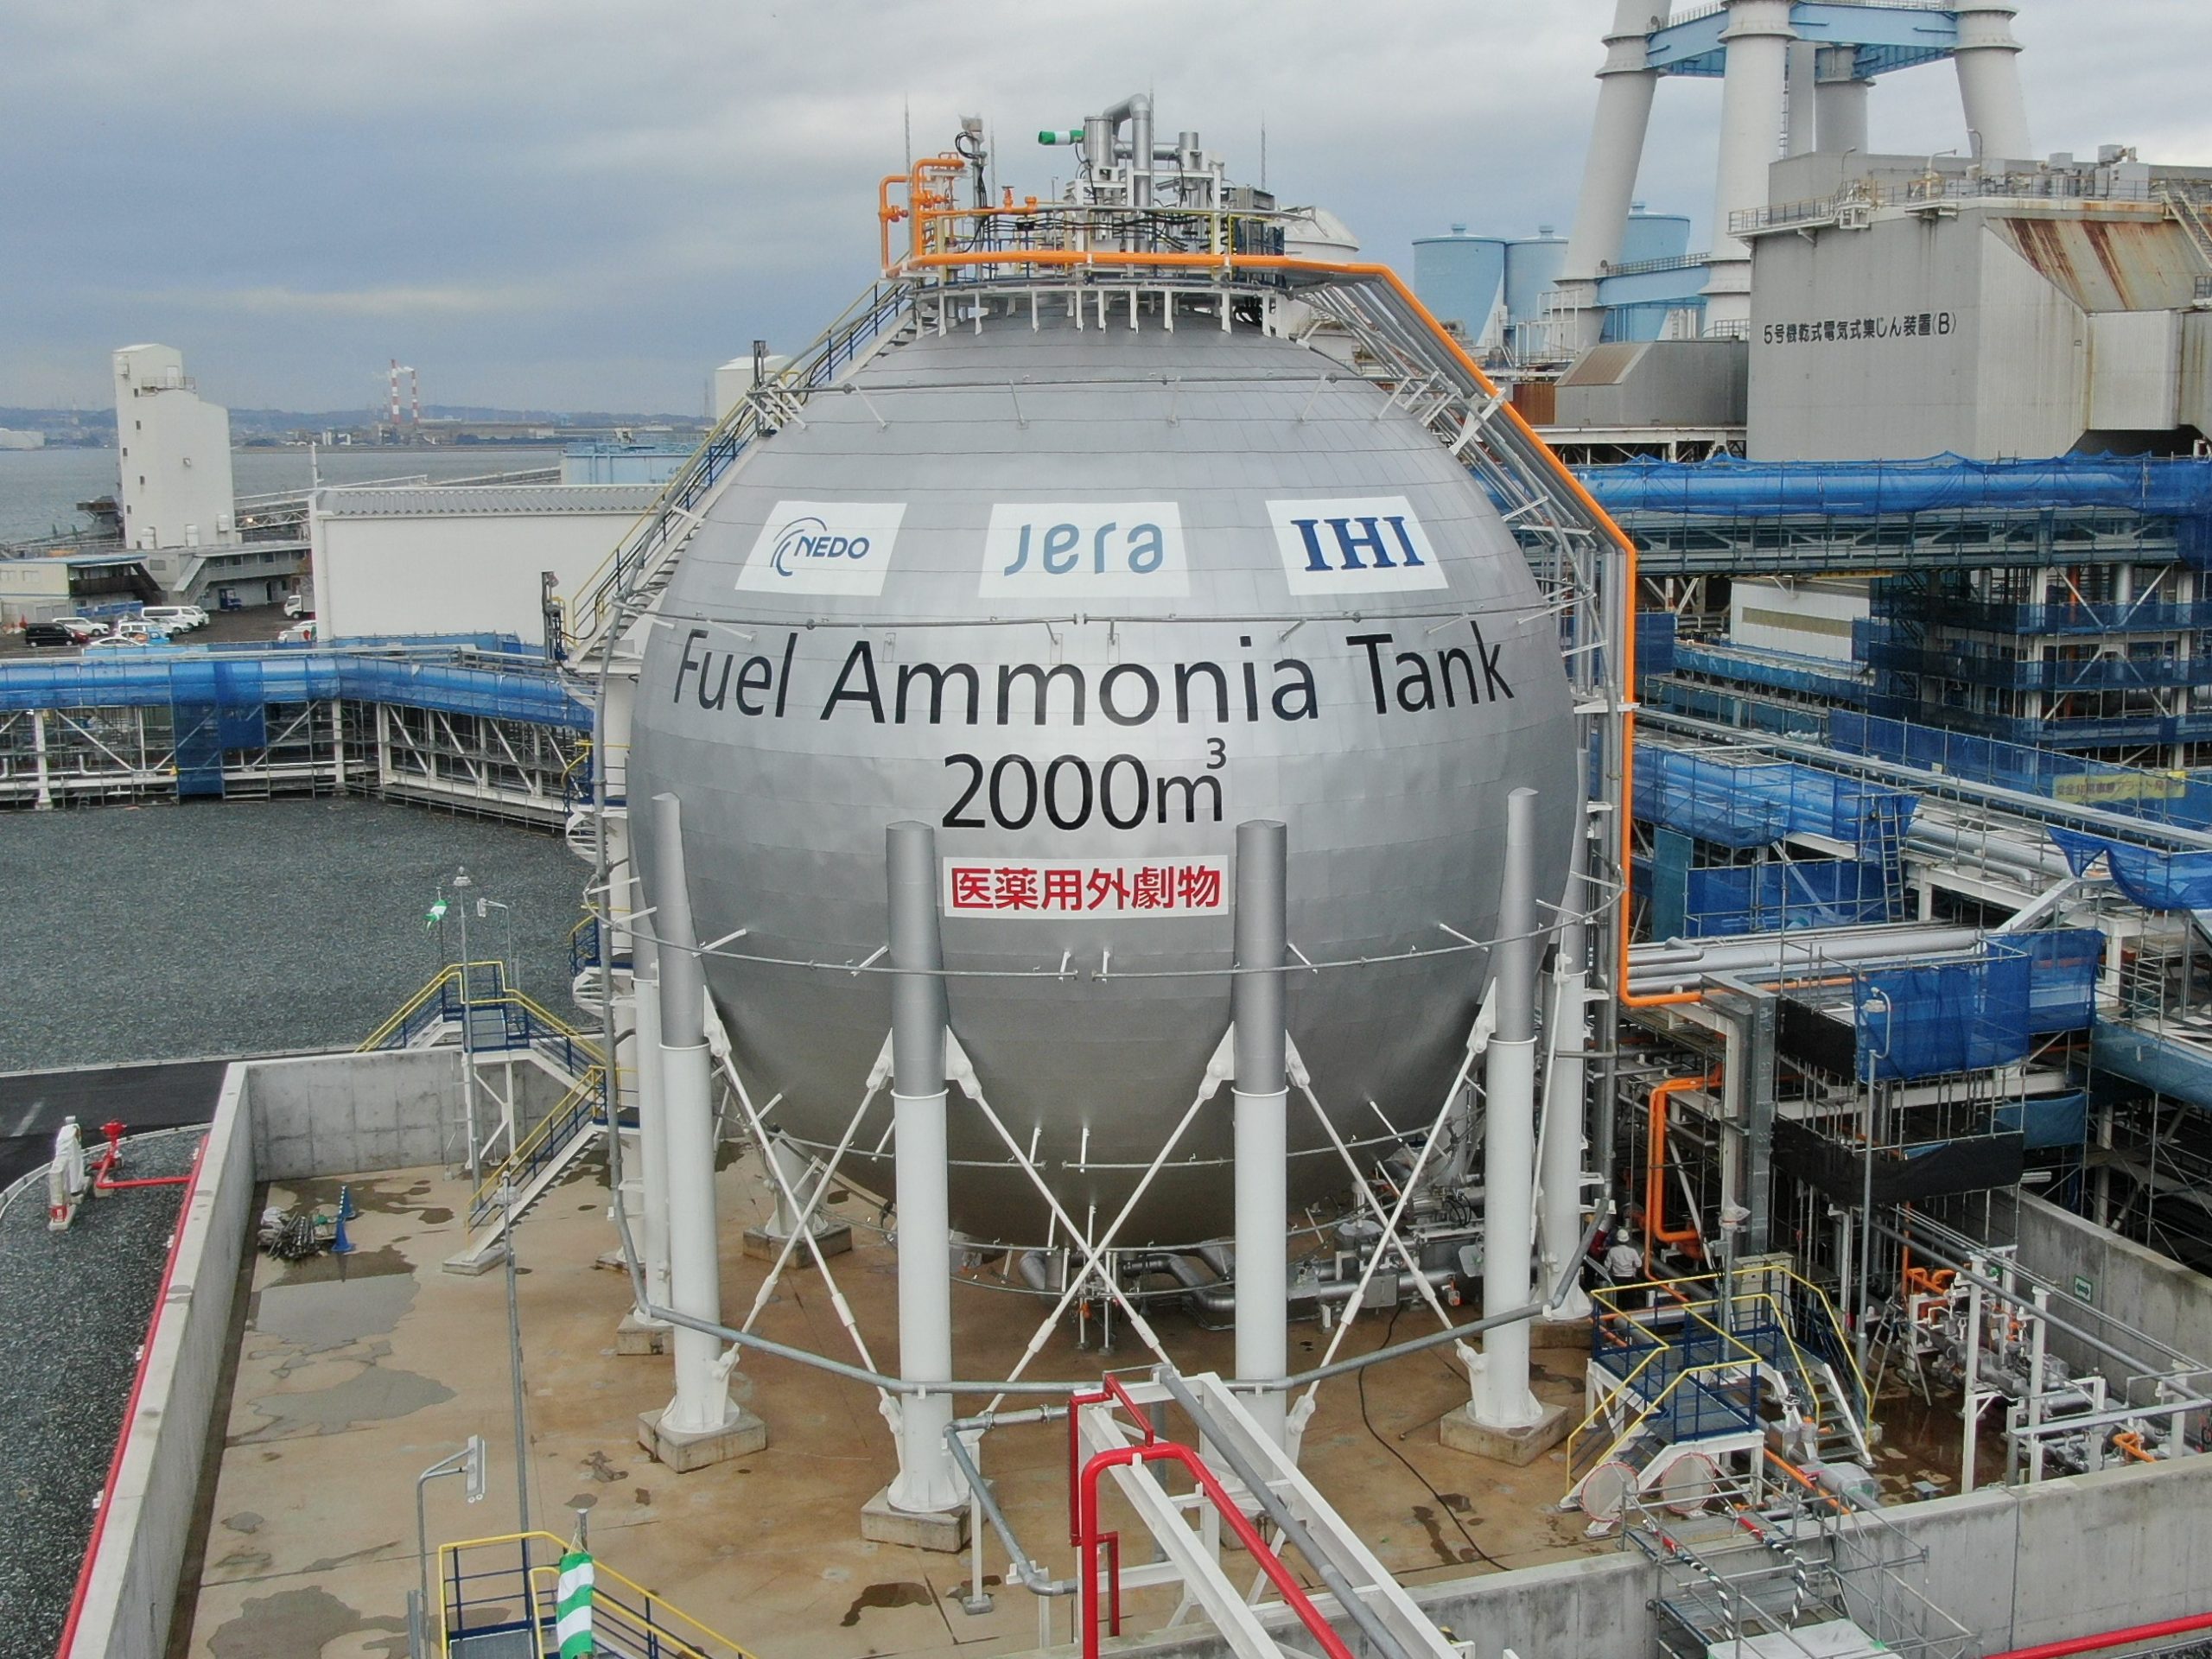
While the power sector has been advanced as a major long term source of demand for emerging low carbon ammonia projects, the pace of development in leading proponents such as Japan and South Korea remains patchy.
The August deadline for talks between the US and Iran came and went, as expected, with no resolution to the conflict. At time of writing, both sides were exchanging tit for tat attacks on ships in the Strait of Hormuz, with Iran claiming that it would be instituting a new ‘exclusion zone’, and no sign of a diplomatic resolution in sight. With the flow of ammonia, urea and other commodities like oil, LNG and sulphur from the Gulf still slowed to a trickle, the summer of high prices and demand destruction looks set to extend well into autumn at least.
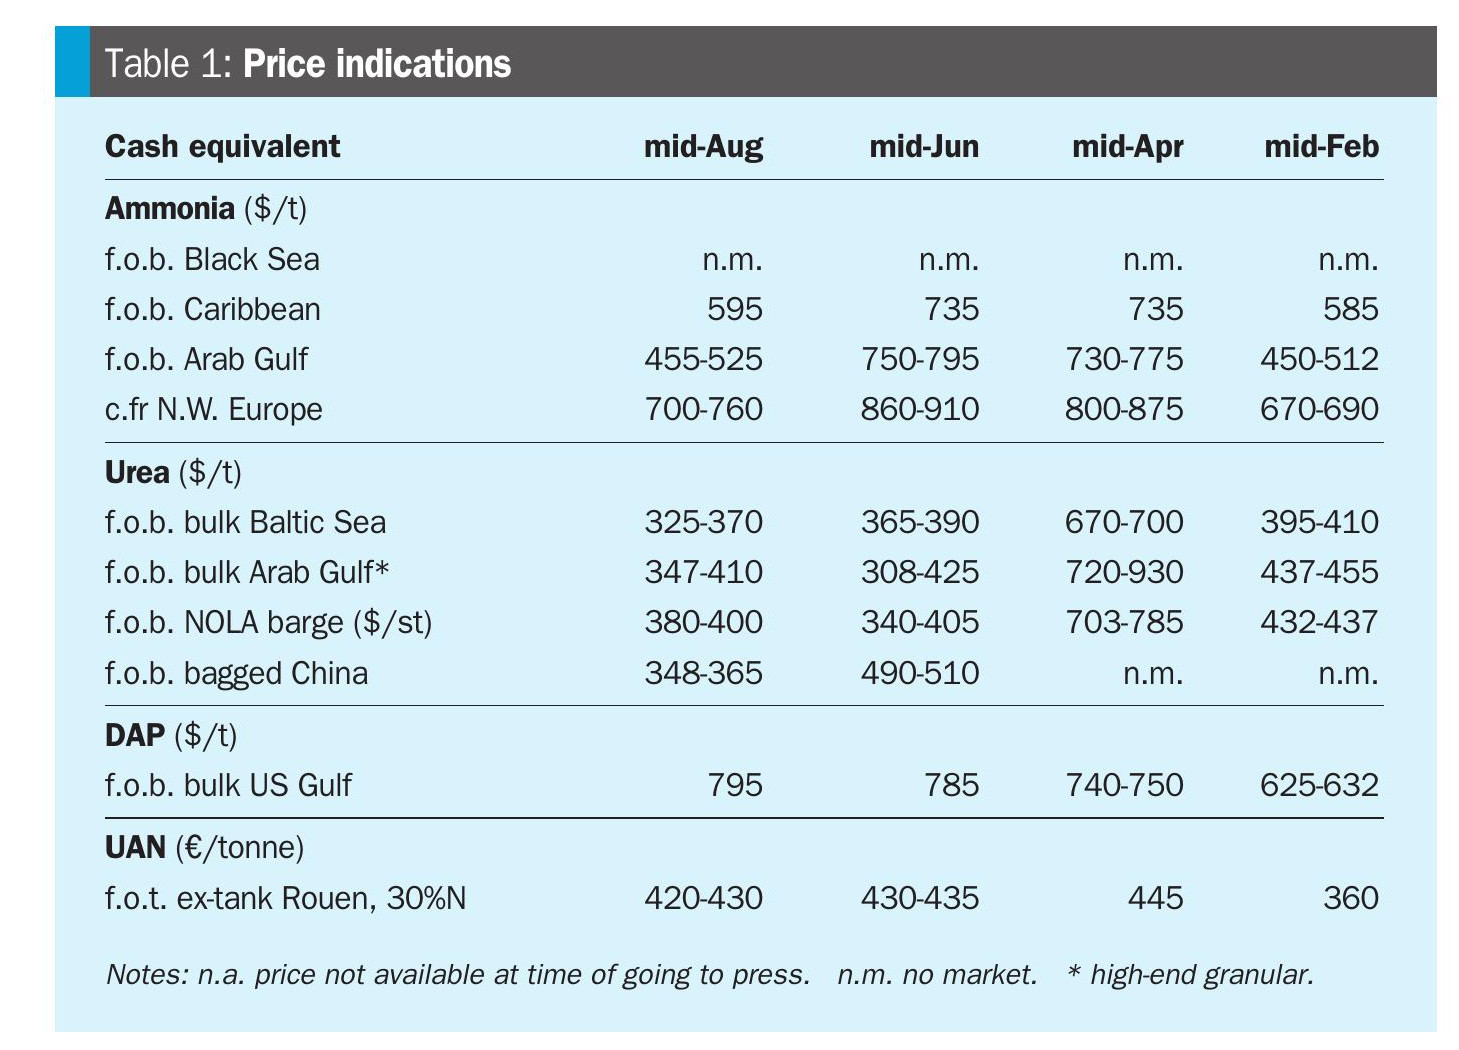
The ammonia market continues be divided on a regional basis during August. In northwest Europe, prices remained high, holding above the $700/t CFR mark, underpinned by high Dutch TTF gas prices, which stood at €63.93/ MWh ($21.5/MMBtu) as of 20 August. The spot market was active, with two cargoes destined for CF Fertilisers in the UK, one an ex-Trinidad cargo supplied by Koch and the other an ex-Algeria cargo supplied by Trammo. Trammo was also linked to a separate, unconfirmed, sale into Poland for Grupa Azoty.
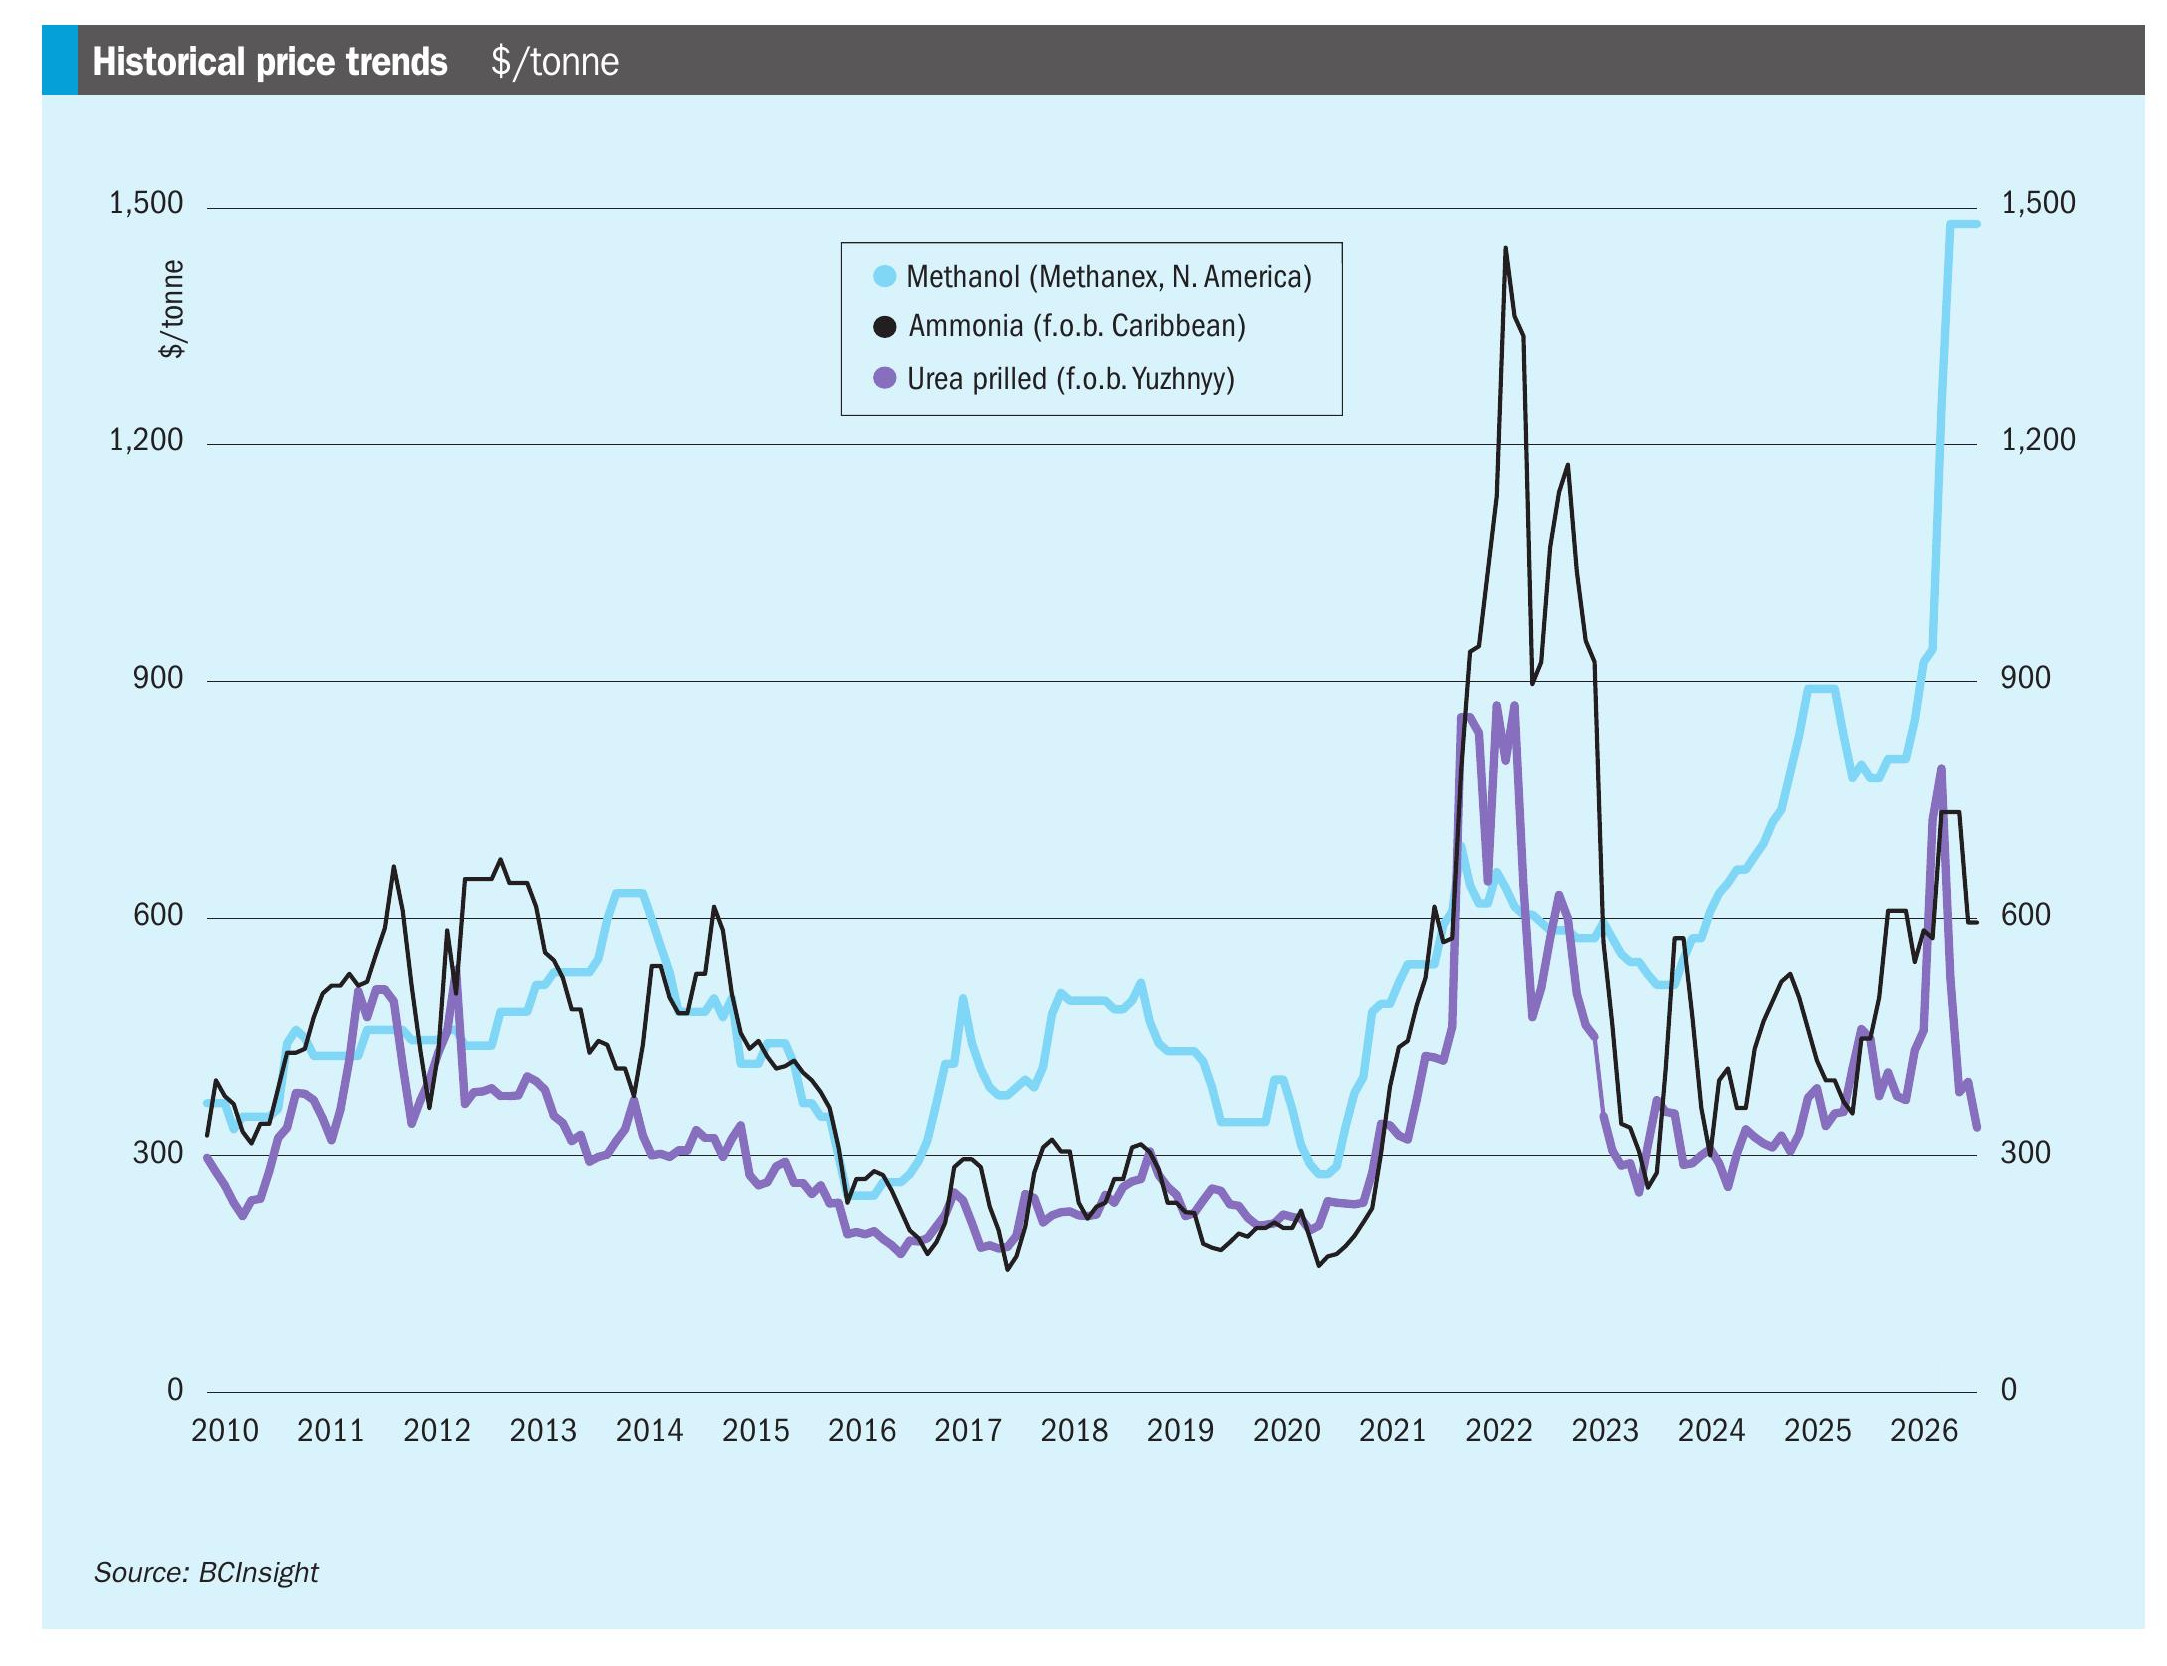
• Prices are expected to hold firm in Europe, though values elsewhere could well undergo further pressure, with Tampa also expected to decline for September.